argenx SE has agreed to acquire Unnatural Products Inc. for $550 million in upfront cash plus as much as $595 million in development and regulatory milestone payments, putting the total potential value of the biotechnology transaction at approximately $1.15 billion. The November 9 agreement gives argenx control of an artificial intelligence-assisted macrocyclic peptide discovery platform that it believes can expand its immunology strategy beyond antibody-based medicines into oral and potentially long-acting therapies.
The structure of the transaction is important because the entire $1.15 billion headline figure is not committed consideration. argenx will fund the $550 million upfront payment from cash on hand, while the remaining $595 million will become payable only if specified development and regulatory milestones are achieved. Both companies’ boards have approved the acquisition, which is expected to close before the end of 2026 subject to customary closing conditions.
The deal is unusual compared with acquisitions built around a Phase 2 or Phase 3 drug candidate. argenx and Unnatural Products have not disclosed a specific lead clinical asset, disease indication or development-stage molecule that accounts for the purchase price. Instead, argenx is acquiring a discovery engine designed to generate macrocyclic peptides against targets that can be difficult to reach with traditional small molecules or antibodies.
That distinction creates both the strategic appeal and the principal uncertainty. argenx is effectively paying hundreds of millions of dollars now for the ability to repeatedly generate future drug candidates rather than purchasing a programme with established human efficacy. The investment therefore depends heavily on whether Unnatural Products can turn its platform into molecules that combine biological selectivity, oral exposure and clinical activity across immune-mediated diseases.
Why is argenx paying $550 million upfront for a drug discovery platform rather than a mature clinical asset?
Unnatural Products has built a platform around synthetic macrocyclic peptides, molecules that occupy a middle ground between traditional small-molecule drugs and much larger biologic medicines. Their ring-shaped structures can potentially bind difficult protein surfaces with high specificity while retaining properties that may allow oral administration or access to targets that conventional antibodies cannot reach.
The company combines machine-learning-guided design with parallel synthesis and direct biological screening to search large numbers of macrocyclic structures. The objective is not simply to create peptides, but to identify molecules with the potency, selectivity and drug-like characteristics necessary to reach historically difficult therapeutic targets.
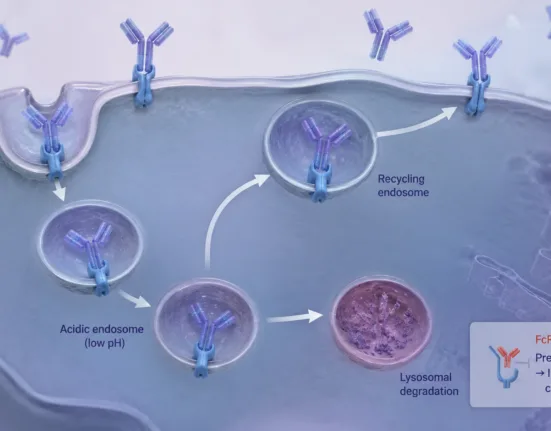
For argenx, those capabilities complement an organisation built primarily around antibody engineering. VYVGART, its commercial FcRn franchise, established the company as a major immunology business, while additional programmes such as empasiprubart and the recently acquired FB102 broaden the mechanisms being pursued. Unnatural Products adds another therapeutic modality rather than merely another molecule.
Management sees that diversity as important for the next stage of growth. Antibodies can be highly selective but frequently require injections or infusions and generally cannot enter cells easily, while well-designed macrocyclic peptides may offer different pharmacological and administration possibilities. If the platform works as intended, argenx could select a therapeutic format according to the biology of each target instead of trying to solve every immunology problem with an antibody.
What does argenx actually receive for the potential $1.15 billion purchase price?
The acquisition includes Unnatural Products’ peptide discovery technology, research organisation and existing portfolio of therapeutic macrocycle programmes. Following completion, the company’s team and leadership are expected to remain at its Santa Cruz, California site, which will become argenx’s dedicated centre for peptide discovery.
Unnatural Products will continue leading discovery activities within a strategic framework agreed with argenx. argenx will contribute its clinical development, regulatory and commercial capabilities once programmes move beyond the discovery stage, creating a division of responsibilities that preserves the acquired company’s research operation while connecting it to a much larger drug-development organisation.
The specific economics also provide information about how argenx is valuing risk. The $550 million cash payment represents the immediate value assigned to the platform, team, intellectual property and existing work, while more than half of the remaining potential consideration depends on future development and regulatory progress.
argenx has not disclosed the exact milestone triggers, individual payment amounts or how many programmes would need to progress before all $595 million becomes payable. The full $1.15 billion should therefore be understood as a maximum potential transaction value rather than the acquisition price that will necessarily be paid.
Why did argenx move from collaboration and minority investment to full ownership?
The takeover did not begin with a cold acquisition approach. argenx already holds a minority stake in Unnatural Products and has worked with the company through a multi-target research collaboration focused on creating oral macrocyclic peptide medicines against immune-disease targets selected by argenx.
Under a collaboration announced in 2025, Unnatural Products was responsible for discovery and development work through the investigational new drug-enabling stage, while argenx obtained options to develop and commercialise resulting candidates. That original agreement carried potential research, development, regulatory and commercial milestones of approximately $1.5 billion plus royalties, illustrating the value argenx had already assigned to successful programmes emerging from the platform.
Full acquisition changes those economics. Instead of paying future royalties and programme-specific collaboration payments while sharing control of the discovery engine, argenx will own the technology and resulting strategic options directly once the transaction closes.
The shift also suggests that argenx gained enough confidence during the collaboration to justify taking platform risk onto its own balance sheet. That does not mean any individual candidate has been clinically validated, but it indicates that the buyer had greater visibility into the technology and research output than would be available in an acquisition based only on public information.
Why are macrocyclic peptides attracting so much pharmaceutical interest?
Drug discovery has long faced a gap between small molecules and large biologics. Traditional small molecules are convenient to manufacture and can often be taken orally, but many disease-causing proteins lack the pockets needed for them to bind effectively. Antibodies can recognise large protein surfaces with exceptional specificity but generally cannot cross cell membranes and are usually administered by injection or infusion.
Macrocyclic peptides are being developed partly to bridge that gap. Their constrained ring structures can create large interaction surfaces while still remaining substantially smaller than antibodies, opening the possibility of binding targets that have historically been difficult to drug.
Oral administration represents one of the most commercially attractive ambitions, although it remains technically challenging. Peptides can be degraded in the gastrointestinal tract and may struggle to cross biological membranes, so achieving reliable oral exposure requires careful control of molecular properties rather than assuming every macrocycle will behave like a tablet-form small molecule.
Unnatural Products’ platform is designed around that medicinal chemistry challenge. The company uses large-scale experimentation and computational approaches to search for structures capable of retaining target engagement while gaining the permeability and stability needed for practical drug development.
The acquisition therefore does not mean argenx already possesses a portfolio of proven oral immunology medicines. It gives the company a platform intended to increase the probability of discovering them.
Could oral immunology drugs change the competitive position of argenx?
Patient convenience has become increasingly important as immunology markets grow more crowded. Many effective biologics require intravenous or subcutaneous administration, creating clinic visits, injection burden or the need for specialised delivery devices.
argenx has already been working to reduce that burden within the VYVGART franchise through subcutaneous formulations and planned autoinjector options. Macrocyclic peptides could take the strategy further if they enable effective oral treatment for targets currently addressed mainly with biologics.
The commercial appeal would extend beyond convenience. Oral medicines may allow broader prescribing outside specialist infusion infrastructure, potentially lower some administration costs and give pharmaceutical companies more flexibility in chronic diseases where patients may remain on therapy for years.
Those advantages remain theoretical for the acquired platform until specific candidates advance into human studies. Oral bioavailability must be sufficient, dosing needs to be practical and the molecules still have to demonstrate the efficacy and safety required to compete with established biologics or conventional small molecules.
The strongest strategic argument is therefore optionality. argenx will be able to explore antibody, peptide and other therapeutic approaches across its immunology targets, potentially selecting the modality that best matches the underlying biology and desired patient experience.
How does the Unnatural Products deal fit with argenx’s $2.2 billion Forte Biosciences acquisition?
The latest transaction follows another major acquisition only months earlier. argenx completed its approximately $2.2 billion purchase of Forte Biosciences in August 2026, adding FB102, an anti-CD122 antibody being developed across autoimmune diseases including celiac disease and vitiligo.
The two transactions target different parts of the drug-development chain. Forte brought argenx a clinical-stage molecule with human proof-of-concept data and a defined biological mechanism, while Unnatural Products brings a discovery platform intended to repeatedly produce future medicines.
Together, the deals show that argenx is using VYVGART-generated cash and profits to construct the next generation of its pipeline rather than depending indefinitely on expansion of one FcRn franchise. That strategy can reduce long-term concentration risk if new programmes succeed, but it also increases the amount of capital exposed to early and mid-stage research uncertainty.
The combined headline value is substantial. argenx has committed approximately $2.2 billion for Forte and another $550 million immediately for Unnatural Products, before accounting for the latter company’s contingent milestone payments.
This spending makes clinical prioritisation increasingly important. A broader pipeline creates more opportunities, but research and development costs rise quickly when multiple acquired programmes move into expensive clinical trials simultaneously.
Can argenx comfortably fund another large biotechnology acquisition?
argenx enters the transaction with a balance sheet capable of absorbing the upfront payment without external financing. Cash, cash equivalents and current financial assets totalled approximately $3.7 billion at September 30, including $2.6 billion in cash and cash equivalents and $1.1 billion in current financial assets.
The company is also generating significant commercial revenue. VYVGART global product net sales reached approximately $1.72 billion in the third quarter of 2026, increasing 54% from the prior-year period and 13% sequentially. Nine-month VYVGART product sales reached approximately $4.53 billion.
argenx reported approximately $500 million of third-quarter profit and $1.3 billion of profit for the first nine months of 2026. That financial profile gives the company far more flexibility to acquire early technologies than a development-stage biotechnology company dependent on equity financing.
The spending is not immaterial, however. Cash and current financial assets had declined from approximately $4.4 billion at the end of 2025, while research and development expenditure reached roughly $1.4 billion during the first nine months of 2026.
Buying Unnatural Products therefore represents capital allocation rather than free optionality. The acquisition needs eventually to produce enough valuable pipeline assets to justify both the $550 million upfront cost and the opportunity cost of deploying capital that could otherwise support internal programmes, additional acquisitions or shareholder value creation.
Why did ARGX shares rise after a deal with no disclosed clinical programme?
argenx American depositary shares closed November 9 at approximately $962, gaining about 3.8% for the session. The shares traded as high as roughly $966 and remained within a 52-week range of approximately $662 to $1,073.
The positive reaction suggests investors did not view the $550 million upfront commitment as an excessive financial burden given argenx’s cash generation and balance sheet. Market commentary also focused on the strategic fit between Unnatural Products’ peptide capabilities and argenx’s existing antibody-based immunology platform.
The movement should nevertheless be interpreted within the stock’s recent momentum. ARGX had already gained 3.6% on November 6 and had risen substantially from its late-October levels, meaning the November 9 move was not occurring in isolation.
The more meaningful market test will come later, when argenx identifies specific targets or development candidates emerging from the platform. Platform acquisitions can generate enthusiasm at announcement but ultimately create value only if the underlying technology repeatedly produces medicines capable of progressing through clinical development.
What are the biggest unknowns hidden behind the $1.15 billion headline?
The most significant uncertainty is that argenx has not disclosed a lead Unnatural Products programme, its molecular target, its intended disease indication or whether any acquired candidate has entered clinical testing. Investors therefore cannot currently assign conventional probability-adjusted values to individual pipeline assets.
The second unknown is the performance of the oral macrocycle technology in humans. A platform can generate potent compounds in laboratory testing while still encountering challenges with absorption, metabolism, safety or therapeutic exposure when administered to patients.
The third uncertainty involves the contingent consideration. argenx could ultimately pay up to another $595 million, but the transaction announcement does not disclose which development and regulatory events trigger those payments. The timing and probability of the additional consideration therefore cannot yet be modelled precisely from public information.
Integration risk also deserves attention. argenx intends to preserve the Santa Cruz operation and its existing leadership, an approach designed to avoid damaging the scientific culture it is buying. The challenge will be providing enough independence for the research team to remain innovative while integrating programme selection, development standards and resource allocation into a rapidly expanding global organisation.
Why does retaining the Santa Cruz team matter to the value of the acquisition?
In platform biotechnology acquisitions, much of the value can reside in scientists and accumulated know-how rather than physical assets. Macrocyclic peptide design involves medicinal chemistry expertise, experimental techniques, screening systems and iterative knowledge that may not be fully captured by patents or software.
argenx is therefore keeping Unnatural Products’ existing team and leadership in Santa Cruz. The site will become its home for peptide discovery, while the acquired organisation will continue leading research within a broader argenx strategic framework.
That structure reduces the risk of buying a scientific platform and then losing the researchers who understand how to operate it. Employee retention will still matter after closing because competition for experienced peptide chemists, computational scientists and drug-discovery specialists remains intense.
Maintaining a dedicated hub may also help prevent the platform from becoming subordinate to argenx’s existing antibody programmes. The strategic logic of the transaction depends on adding a genuinely different modality, not simply using macrocyclic peptides as another supporting technology within an antibody-centred organisation.
What will determine whether argenx’s $1.15 billion peptide bet pays off?
The first meaningful milestone will be disclosure of actual drug programmes. Targets, disease indications, preclinical profiles and development timelines will allow investors and clinicians to judge whether Unnatural Products is producing molecules with properties that could meaningfully expand argenx’s portfolio.
Progress into investigational new drug-enabling studies and eventual human trials will provide a more demanding test. Oral exposure, pharmacokinetics, target engagement and safety will determine whether the platform can translate medicinal chemistry promise into viable medicines.
A successful programme would also need to compete with rapidly advancing immunology standards. Convenience alone is unlikely to be enough if an oral macrocyclic peptide cannot match or approach the efficacy of established biologics in serious autoimmune disease.
The acquisition nevertheless gives argenx something strategically different from another pipeline asset. Forte Biosciences expanded the company with a specific clinical-stage antibody, while Unnatural Products expands the range of therapeutic formats argenx can attempt to create.
That distinction explains why the company is willing to pay $550 million before a publicly disclosed clinical product has emerged. argenx is betting that future immunology leadership will depend not only on discovering the right biological targets but also on having enough therapeutic technologies to drug those targets in ways that patients can realistically use.
The transaction will look inexpensive if the platform eventually produces even one major oral immunology franchise. If the acquired science struggles to cross the gap from sophisticated discovery technology to clinically effective medicines, the same $550 million upfront payment will look far more aggressive. The answer is unlikely to come from the acquisition itself, but from the first human data generated by the molecules argenx has just paid to discover.